In France, it is simple and often duty-free. In London or New York, the same deed can prove costly. A three-minute guide.
I. On the French side: an effective tool
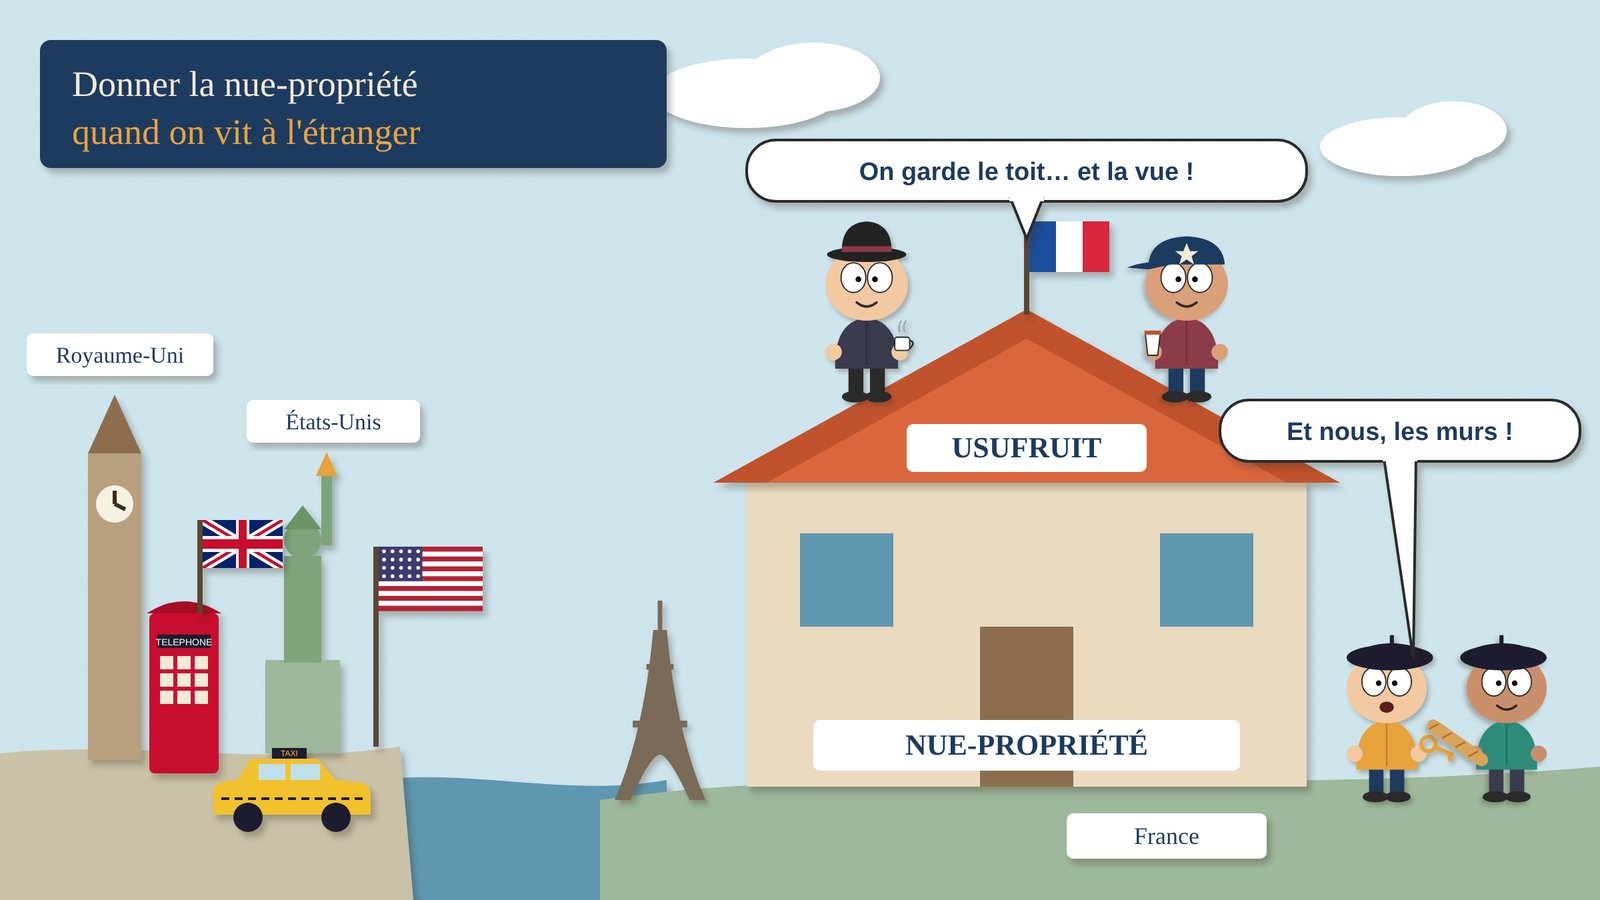
A gift of French property with a reserved usufruct is governed by French law, even though English law and the law of most US states do not recognise the usufruct as a property right: they treat it as a life interest or a life estate. The deed can be signed from abroad, under a power of attorney in authentic form executed remotely before the French notary by video link (Decree No. 2020-1422 of 20 November 2020).
Duty is charged on the bare ownership only: 60% of the value if the usufructuary is between 61 and 70 (CGI, art. 669). Each child has a €100,000 allowance per parent, wherever they live, less any gifts made in the previous fifteen years. When the usufructuary dies, the child becomes full owner with no further duty (CGI, art. 1133). For a couple, a reversion of the usufruct protects the survivor and is exempt between spouses (CGI, art. 796-0 bis).
Example: a couple aged 65 gives the bare ownership of a €600,000 house to their two children. Each child receives €90,000 from each parent: no duty is payable in France.
II. Abroad: the real difficulty
United Kingdom. No treaty covers lifetime gifts: the treaty of 21 June 1963 applies to estates only. Since 6 April 2025, inheritance tax reaches the worldwide assets of long-term residents (10 tax years out of 20). HMRC treats a usufruct created since 22 March 2006 as a settlement: the gift is an immediately chargeable transfer of the full value of the property, taxed at 20% above the £325,000 nil-rate band and then subject to periodic charges; the property may also remain in the donor’s estate as a gift with reservation of benefit. This view is contested, but it is HMRC’s stated position. The gift is also a disposal for capital gains tax (18% or 24%), reportable by 31 January following the end of the UK tax year.
United States. The treaty of 24 November 1978 covers gifts: France taxes the property and the US credits the French tax. But federal law disregards the retained usufruct (IRC § 2702): as a precaution, the gift should be reported at the full value of the property, without the $19,000 annual exclusion, because bare ownership is a future interest. The $15,000,000 basic exclusion in 2026 often avoids the tax, not the filing (Form 709, due 15 April of the following year). On death, the property is brought back into the US estate (§ 2036). The treaty covers federal tax only; some states have their own rules.
Key point: one deed, three tax readings. Attractive in France, a gift of bare ownership must be cleared by an adviser in the country of residence before signing.
FAQ
Do we need to come to France to sign?
No. The power of attorney in authentic form is executed remotely before the French notary, by video link.
Will the children pay duty when their parents die?
Not in France on this property. The UK and the US may, however, bring it back into the estate.
Is double taxation avoided?
For the US, the treaty provides a tax credit, but the two countries do not tax the same value at the same time. For the UK, no treaty covers lifetime gifts.
Chambarière & Associés advises British and American clients, in French and English: +33 5 56 44 00 65 or our contact form.
References: French Tax Code (CGI), art. 669, 750 ter, 779, 796-0 bis and 1133; France–UK treaty of 21 June 1963 and France–US treaty of 24 November 1978; Finance Act 1986, s. 102 and 102A; HMRC Inheritance Tax Manual, IHTM27054; IRC §§ 2036, 2503 and 2702. Up to date as of 31 October 2026. For information only: this article is not a substitute for advice.